
Two English-speaking countries with near-identical smartphone habits have reached opposite answers to the same governance question, and 2026 is the year the gap got easy to measure. Ireland now runs its gambling sector through a single national authority created by one act of parliament. The United States runs its through fifty legislatures, none of which has any obligation to agree with the others. Same phones, same app stores, same house edge. Completely different machinery behind the install button.
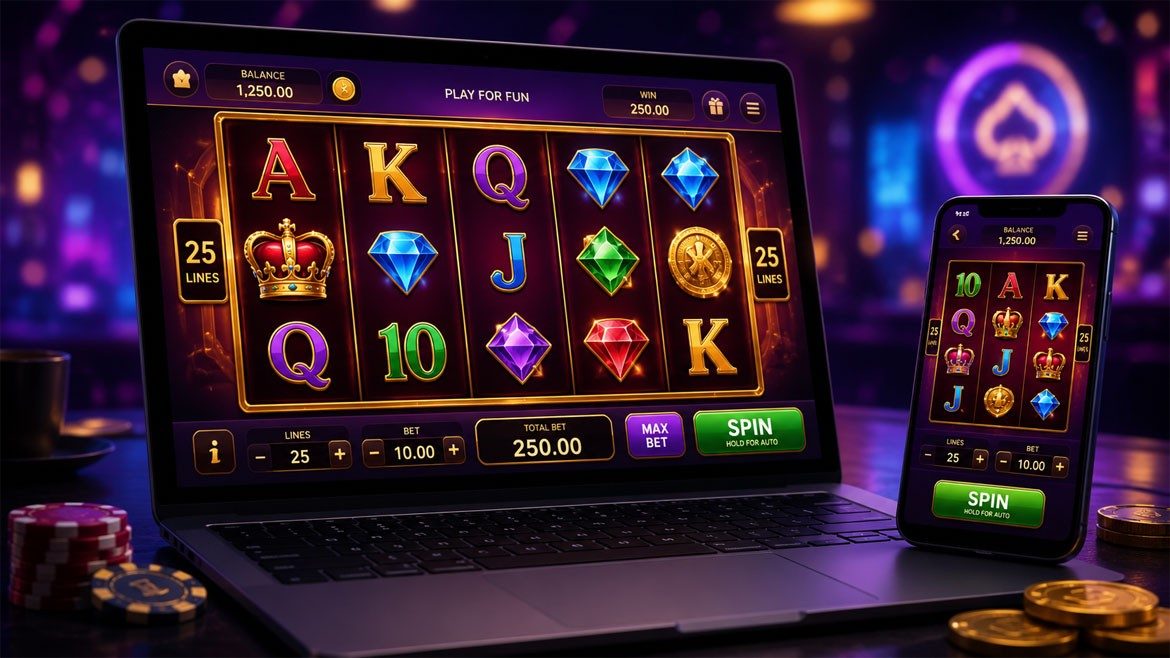
The comparison only works if you separate the product formats first, because regulators do exactly that. A real-money casino app that takes deposits and pays out cash sits in one legal box. A free-to-play social casino that sells coins with no cash value sits in another. The sweepstakes model that grew up between the two sits in a third box that American courts and attorneys general are actively fighting over right now. GamingToday publishes ongoing insights into free-to-play social casino options, and the line it draws between coin play and cash wagering is the same line that decides which rulebook applies to a given app.
For anyone who builds, publishes or covers games, that’s the practical point hiding inside a dry policy comparison. The regulatory question is rarely “is gambling allowed here.” It’s “which of the three boxes does this product fall into, and who gets to decide.”
Ireland Chose One Address for the Entire Sector
 Ireland’s Gambling Regulation Act 2024 replaced a scattered set of older statutes with a single framework and handed it to a single body, the Gambling Regulatory Authority of Ireland. One authority licenses betting, gaming and lotteries. The same authority sets advertising limits, runs a national self-exclusion register, and administers a social impact fund paid for by an industry levy. If you want to operate in Ireland, there is one door.
The advantages are unglamorous and real. An operator files one application rather than several. A player who wants to shut themselves out of every licensed site does it once, in one place, rather than site by site. A journalist chasing an enforcement story knows which press office to call. Compliance costs fall for everyone except the smallest entrants, who face a single fixed hurdle rather than none at all.
The cost is concentration. A national regulator is also a single point of failure. If it is slow to issue licences, the whole market waits. If it reads a product category wrongly, it reads it wrongly for the entire country at once, and there is no second jurisdiction next door running the experiment differently and producing a counterexample. Ireland traded away its internal control group.
America Never Had Ireland’s Option
The United States did not weigh centralisation and reject it. Gambling authority sits with the states as a matter of structure, so a patchwork is the default outcome rather than a decision anyone made. Congress could narrow that, and mostly hasn’t.
As of August 2026, seven states allow legal real-money online casino play: New Jersey, Pennsylvania, Michigan, West Virginia, Connecticut, Delaware and Rhode Island. Maine legalised in 2026 but has not gone live. New Jersey launched in November 2013, which means the American market has close to thirteen years of continuous operating data from one state, covering tax receipts, problem-gambling referrals, payment fraud patterns and operator failures. Online sports betting spread across far more states in far less time. Casino gaming has moved slowly because state legislatures keep weighing it against their own commercial casino tax base.
That slowness is a feature of federalism doing its job, not evidence of paralysis. Six states have followed New Jersey since 2013 with the benefit of watching what happened there first. Ireland had no comparable domestic evidence to draw on and had to reason from other countries’ experience instead.
The Tradeoff Has a Price Tag on Both Sides
Here’s the honest version, and I’ll state it once rather than circling it. A national framework buys consistency and pays for it in local flexibility. A state-by-state framework buys local control and pays for it in coherence. Neither is free, and neither side of that trade is obviously superior in the abstract.
Where I’d take a position: for a product distributed over a single internet, coherence is worth more than defenders of local control usually concede. Consumers cross borders constantly, marketing does not stop at a state line, and a fragmented map mostly benefits whoever is willing to operate in the gaps. A player in a state with no regulated option does not stop playing. They play somewhere with no consumer protection attached.
The counterweight is that fragmentation generates evidence. Thirteen years of New Jersey data existed before Rhode Island committed to anything, and that is a genuine asset a unitary system cannot produce internally. The choice is really between one confident answer and fifty noisy ones.
Format Beats Geography When You’re Working Out the Rules
 Neither system treats every format the same way, which is why arguments about “gambling regulation” so often talk past each other. Free-to-play social casino apps that sell virtual coins with no redemption path are generally handled as games with in-app purchases rather than as wagering. Real-money casino apps that accept deposits and pay cash sit squarely inside gambling law. Almost every hard question in 2026 concerns the ground between them.
The sweepstakes model occupies that ground deliberately. It runs on two currencies: Gold Coins, which carry no cash value, and Sweeps Coins, which can be redeemed at roughly one dollar each once a playthrough requirement is met. An alternative method of entry, usually a mail-in request or a daily free claim, is legally required so the promotion is not a lottery. Operators frame this as meaning that no stake is placed. That is their characterisation, and it is precisely the characterisation regulators are now testing rather than an agreed legal fact.
The Sweepstakes Fight Is Where Fragmentation Gets Expensive
This is where the American map stops being an interesting comparison and starts costing companies money. Florida’s Attorney General sued sweepstakes operators in August 2026, and, notably, sued payment processors alongside them. California’s AB 831 was signed on 11 October 2025 and took effect on 1 January 2026, extending liability beyond operators to vendors and suppliers. Connecticut, New Jersey and Montana have all acted as well. Nothing here is settled, and legality genuinely varies by state.
The structural lesson is not simply that rules differ. It is that liability has started moving down the supply chain. A studio licensing a game engine, a processor moving funds, an affiliate placing traffic, all of them are now inside the exposure zone in at least some states rather than sitting comfortably behind an operator. Under Ireland’s model, a comparable question gets answered once and applies everywhere. Under the American model, the same product can be lawful, tolerated and actionable simultaneously, depending on which side of a state line the customer opened the app on. Compliance stops being a legal opinion and becomes a fifty-way risk register that has to be maintained continuously.
Canada Runs the Same Experiment Inside One Country
Canada is worth a look because it sits between the two models rather than at either pole, and it gives the comparison a third data point. Provinces hold the authority, but each province that opens tends to build something internally coherent.
Ontario opened to private operators on 4 April 2022, splitting the job between two bodies: the Alcohol and Gaming Commission of Ontario as regulator, and iGaming Ontario as the entity that conducts and manages the market. Minimum age is 19. In fiscal 2024-25 the province recorded C$82.7bn wagered and C$3.2bn in gaming revenue, which is the kind of number that tends to change neighbouring provinces’ minds.
Alberta duly changed its mind. Its market opened on 13 July 2026 under the iGaming Alberta Act, with 22 platforms live at launch and more than 27 by mid-August 2026, while the existing PlayAlberta site continued to operate alongside the private entrants. Minimum age is 18. British Columbia has not moved and still offers only BCLC’s PlayNow, with a minimum age of 19.
Three provinces, three positions, one country. The Canadian version shows that fragmentation and coherence aren’t strictly opposed. You can have a patchwork between jurisdictions and a clean single framework inside each one.
Enforcement Capacity Decides Whether Either Model Is Real
A rulebook is only worth the institutional will and budget behind it. Ireland concentrates enforcement in one authority, which makes accountability obvious and makes under-resourcing obvious too. There is nowhere to hide a backlog. But a national regulator’s reach ends at the border, and an offshore site that never applied for an Irish licence is not deterred by the threat of losing one.
The American answer is messier and, in one respect, sharper. Fifty enforcement postures produce inconsistency, but they also produce experimentation in method. The Florida action is the clearest example: going after payment processors rather than only operators targets the part of the chain that has a licence worth protecting and a compliance department that answers the phone. Payments, not app stores, turned out to be the pressure point. That tactic will get copied, in the US and elsewhere.
What Regulation Buys a Player, and What It Never Will
Worth being blunt about the limit here. The house edge is built into every one of these products by design, in Dublin and in Detroit alike. Regulation governs whether you get paid, not whether you win. No licensing regime changes the maths.
What a licence does buy is narrower and still valuable: segregated player funds so a collapse doesn’t take deposits with it, a complaints route that ends somewhere other than a support inbox, published game rules, identity checks that make age limits real, and self-exclusion that binds across operators instead of one at a time. Those are the things absent from an unlicensed site, and their absence is the actual argument for regulated markets, not any claim about better odds. For anyone tracking how these markets develop week to week, GamingToday on Facebook posts regular coverage of state and provincial changes.
If play stops being fun, support exists and it’s free. In the US that’s 1-800-GAMBLER. In Ontario, ConnexOntario is on 1-866-531-2600.
Neither Framework Is Finished, Which Is the Useful Part
Ireland’s authority is still building out its licensing regime in practice, and practice is where centralised frameworks either prove workable or don’t. The American map keeps moving: Maine legalised in 2026 and has yet to launch, and the sweepstakes cases filed in 2026 have not been resolved. Alberta’s operator list was still growing through August 2026.
So judge trajectories rather than snapshots. Ireland’s test is whether one body can move fast enough to keep pace with product design that changes quarterly. America’s test is whether fifty jurisdictions can converge on anything without being made to. Both tests are live.
For a reader deciding what to actually do with any of this, the useful question isn’t which country got it right. It’s a much smaller one, asked before you tap install: which named body licenses this app, is this a real-money product or a coin-based one, and can you find the redemption or withdrawal terms in writing without contacting support. If you can answer all three in under a minute, the framework behind the app is working. If you can’t, the map matters a lot less than the answer you couldn’t find.
Figures and regulatory status current to 28 August 2026.